APREA Logo

Knowledge Hub

Summary:

As the year unfolds, conflict is becoming a defining global theme. Whether in trade, technology or geopolitics, competition and confrontation are increasingly shaping the economic outlook. Beginning in Iran, hostilities resumed in July following a brief respite, sending energy prices sharply higher in the process. The global economy has so far proven resilient to what Fatih Birol, head of the International Energy Agency, described as the “biggest energy security threat in history”. This resilience reflects weaker energy demand, particularly across Asia Pacific, as well as a substantial drawdown in global inventories, helping to keep the market broadly balanced.

However, reserves have fallen sharply, with inventories held by OECD nations reaching their lowest level since 1990, even before the recent US Iran framework agreement. This places renewed focus on the duration of the conflict, as the oil market’s ability to absorb disruption will diminish over time. The likely result is greater price volatility (even if we get a new deal), with implications extending well beyond energy markets through inflation, consumer and business sentiment, and the fiscal and monetary policy outlook.
Key Takeaways

Climate adaptation is a business necessity and should no longer require debate or justification

Panellists stressed that organisations are already experiencing climate impacts, such as productivity loss and vulnerability of assets, and should move beyond debating whether adaptation is necessary. The focus should be on planning and scaling solutions to protect assets, operations and long-term business viability rather than convincing leadership that climate risks are a threat to the business.

Bridging the gap between climate risk assessment and investment requires adaptation to be expressed in financial terms

While many organisations are conducting climate risk assessments, translating findings into action remains challenging. Securing investment requires a clear business case that quantifies financial value of adaptation through metrics such as avoided losses, energy savings, carbon pricing, and asset value protection. Timing this process with financial windows is also vital to ensure that solutions are actionable with appropriate investment. Adaptation initiatives are more likely to secure investment when benefits are articulated in financial terms and aligned with existing capital planning cycles.

Key findings include:

  • 85% of investors expect to increase Living investment over the next five years.
  • Investors are increasingly favouring stabilised, income-producing and defensive Living assets. Recent volatility has prompted half of respondents to report a greater preference for stabilised, income-producing assets, yet only 17% expect stabilised acquisitions to be their most likely deal structure over the next one to three years, reflecting the limited availability of institutional-grade stock outside Japan. The resulting imbalance, combined with a challenging development environment, is pushing capital towards alternative routes to market, with 73% actively considering repositioning or change-of-use strategies.
  • Australia/New Zealand and Japan rank clearly ahead of other APAC markets for prospective investment, reflecting the combination of institutional scale in Japan and housing undersupply underpinning growth potential in Australia.
  • Market opacity remains a constraint on investment. The buyer-seller pricing gap is the leading investment challenge, identified by 44% of respondents, followed by development viability (29%). Limited transaction evidence and inconsistent transparency are making it harder for investors to price assets and deploy capital.

Data centres have become a core pillar of infrastructure investment across Asia Pacific.

Driven by AI adoption, cloud expansion, enterprise digital transformation, and digital sovereignty initiatives, the sector continues to attract significant capital. At the same time, constraints around power, land, and development capacity are reshaping how investors, operators, and developers identify and secure growth opportunities.

As competition intensifies across the digital infrastructure sector, access to reliable market intelligence and robust investment benchmarks remains limited in many Asia Pacific markets. Understanding the forces shaping performance, risk, and long-term value creation has never been more important.

The latest edition of the Asia Pacific Data Centre Investment Landscape 2026 provides a comprehensive analysis of the trends transforming the region’s data centre sector, with insights spanning 14 key markets.

Download the report to gain insights into:

  • Where capital is flowing across Asia Pacific’s data centre markets
  • Which locations are emerging as the region’s next digital infrastructure hubs
  • The key drivers shaping investment decisions and market performance
  • Trends that will define future growth and value creation opportunities

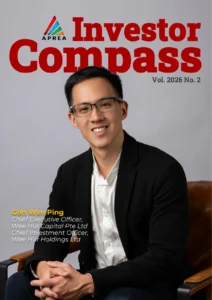
Goh Wee Ping on

Leadership, Discipline and Real Assets Growth

In APREA’s Real Assets, Real People, we speak with leaders shaping the future of Asia Pacific’s real assets industry, exploring the ideas, decisions and leadership principles behind their organisations’ growth. In this edition, Goh Wee Ping shares his perspectives on the shift from real estate assets to operating platforms, the growth of PBSA, the role of AI, and what it takes to build resilient businesses beyond market cycles.

“Asia Pacific remains a key growth engine for branded residences, but its next chapter will be defined by the breadth of its markets,
not the scale of its leading ones.”

Asia Pacific is currently the second most established branded residential region globally, accounting for approximately 23% of all completed schemes worldwide. Whilst the region continues to demonstrate impressive momentum, with a further 187 projects expected to be delivered by 2032, the nature of its growth story is evolving. Although substantial in absolute terms, this growth rate of 97% is level with the Americas and falls behind both Europe and, most notably, the Middle East and Africa, which has emerged as the industry’s fastest- growing region.

Rates set the direction, not fundamentals. Leasing is strong and supply is tight across the region, but neither re-rates the sector while the regional rate path stays hostage to oil and therefore to the Gulf. The August 7th US payroll print (-23,000, with 103,000 of downward revisions and average hourly earnings at 3.2% YoY, the softest since May 2021) cut September hike pricing to 42-44% and pushed the risk to October. Core CPI is stable at 2.6% and justifies a hold.

Japan. Results are done and mixed. Mitsui Fudosan’s 1Q fall was pre-guided, with every greater-Tokyo renewal this fiscal year settled at a higher rent. Tokyo Tatemono beat and raised to record guidance on a JPY 26.1bn property sales gain, but residential operating profit fell 83.2%, which undercuts the argument that condominiums are unaffected by higher rates. Central-five-ward asking rents have accelerated to +11.4% YoY from +5.5% in December 2025. The constraint is the BOJ at 1.00%; consensus sees 1.25% by December and we would not be surprised by September. Sankei Building first-round bids near JPY 1tn against a JPY 500-800bn expectation argue against cap rate softening.

Australia. Guidance is the risk into full-year reporting, not results. Stockland and Mirvac have corrected on residential and EV/EBITDA is back to just above 2022 trough levels, but hedge ratios are higher than in 2022 and in-place debt costs are already high, so we do not expect material deterioration.

Hong Kong. Mid-market residential is supported by end-user demand while luxury continues to suffer. Capital returns are the theme: Wharf REIC lifted its payout ratio to 90% and the stock closed up 13.7%, Link has committed disposal proceeds to buybacks, and we have written to Fortune REIT urging the same treatment of Stars of Kovan proceeds.

Singapore. A non-event, with CICT on August 12th the last major report. Paragon at a 3.9% entry yield against Asia Square Tower 2 at 3.0% lifts pro forma FY25 DPU 2.1%.

India’s renewable energy sector has witnessed unprecedented growth over the past decade, driven by ambitious policy reforms, declining technology costs, and strong investor participation. With installed renewable energy capacity expanding rapidly and the country targeting 500 GW of non-fossil fuel capacity by 2030, the sector is expected to require investments exceeding USD 190-215 bn over the remainder of the decade. While traditional funding sources such as project debt, private equity, strategic investments, and foreign direct investment have played a pivotal role in supporting this growth, sustaining the next phase of expansion will require more efficient mechanisms for capital recycling.

KEY TAKEAWAYS

  • A total of 22,290 rental contracts of island-wide private residential properties (excluding ECs) commenced during the quarter, up 5.1% from the 21,203 contracts recorded in the previous quarter.
  • The URA rental index for non-landed private residential properties rose 0.4% QoQ.
  • Based on Savills basket of high-end non-landed residential properties, the average monthly rent continued its upward trajectory, rising by 1.4% QoQ.
  • Despite limited new completions, the overall vacancy rate of completed private residential properties (excluding ECs) rose to 6.4% in Q2/2026.
  • While Singapore’s economic growth in 2026 is expected to outperform the official 2% to 4% forecast, the benefits to the residential leasing market may be limited. Mixed free cash flow trends among MNCs could restrain expatriate deployment overseas, while the removal of the 15-month wait-out period for private homeowners moving to HDB flats may reduce domestic leasing demand. Accordingly, we maintain our view that private residential rents will remain broadly flat in 2026.