APREA Logo

Knowledge Hub

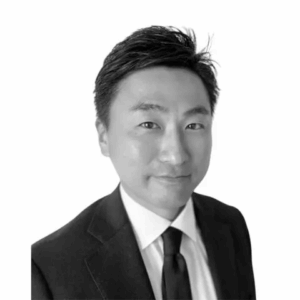
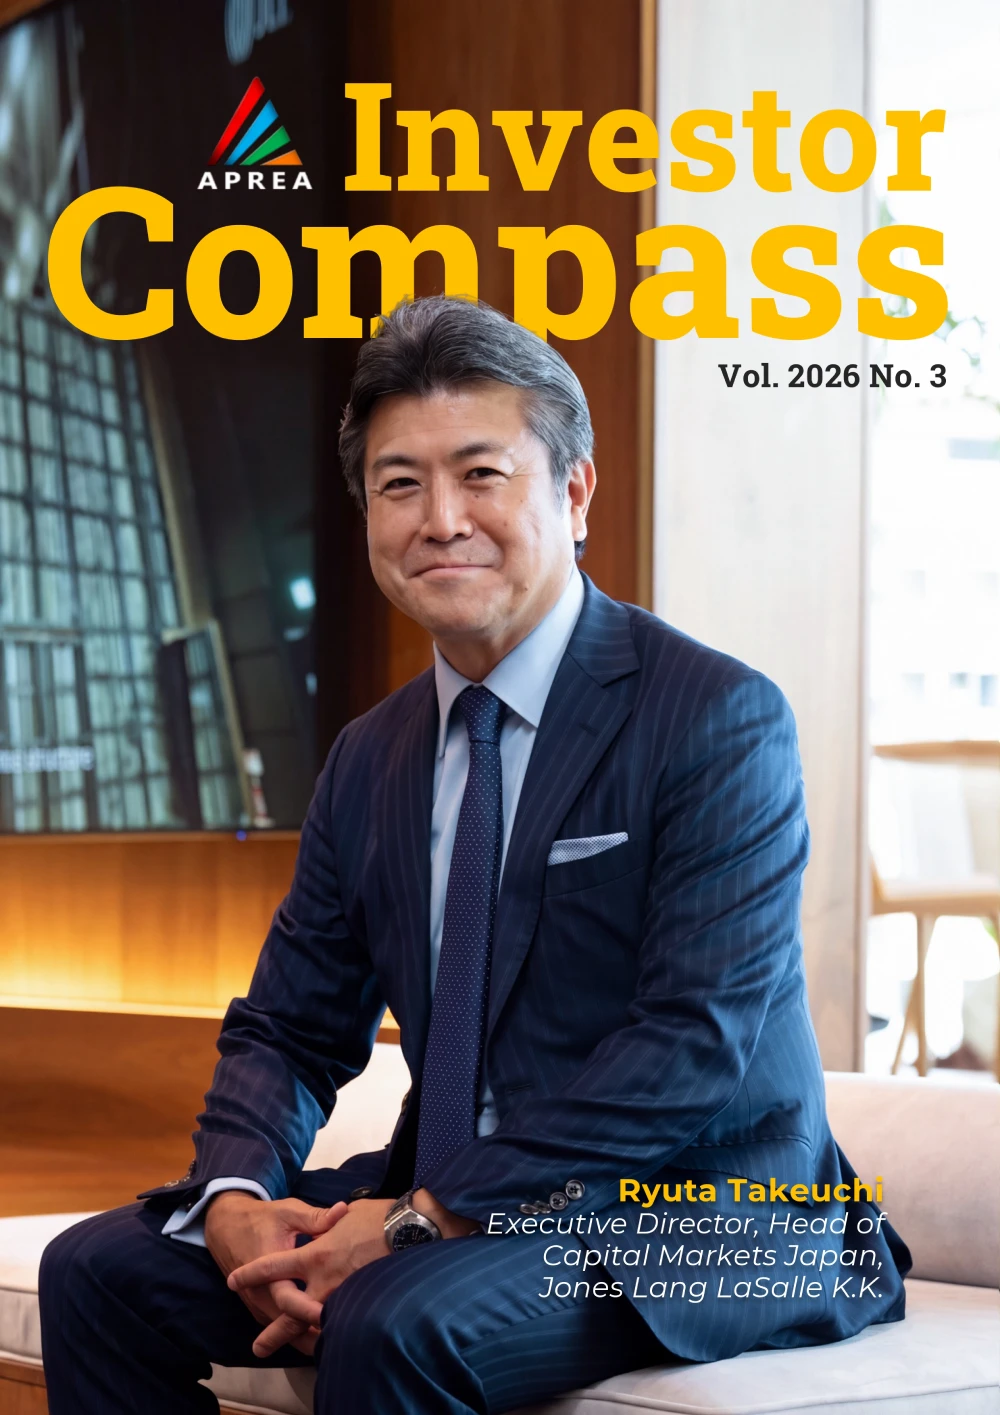
APREA Investor Compass featuring Ryuta Takeuchi (JLL)

In APREA’s Investor Compass, we speak with leaders shaping the future of Asia Pacific’s real assets industry, exploring the market trends, investment themes and leadership perspectives influencing capital allocation across the region.

In this edition, Ryuta Takeuchi of JLL shares his views on Japan’s expanding real estate investment market, the rise of new asset classes and regional opportunities, the changing expectations of global institutional capital, and the capabilities companies need to compete in a more complex investment environment.

Highlights:
Real Assets, Real People – Ryuta Takeuchi, Executive Director, Head of Capital Markets Japan, Jones Lang LaSalle K.K.
Knowledge Brief – Expansion of Investment Targets for J-REITs: Increased Investment in Operational Assets, Such as Data Centers
TrendWatch – India in Focus: GCC Boom and Institutional Capital Drive Real Estate’s Next Growth Chapter
Growth in global prime residential prices strengthened during the second quarter. The latest annual rate of 2.6% represents a recovery from the opening months of the year, while remaining consistent with a relatively measured phase in the global luxury housing cycle.

Mumbai rose by 2.0% and 1.7%. Outside Asia, Nairobi delivered the second- strongest quarterly result in the index, at 5.0%, followed by Vienna at 4.6% and Stockholm at 4.0%.The results suggest that short-term momentum is becoming more geographically dispersed, even as Asian cities retain their prominence in the annual ranking.

Asia’s infrastructure investment cycle is broadening beyond traditional transport and logistics into power grids, energy storage and digital infrastructure, driven by urbanisation, supply-chain shifts and rising electricity demand from AI and data centres. The Asia Pacific is expected to account for more than half of the projected USD151.1 trillion in global infrastructure investment needs through 2050, with transmission, distribution, and utility-scale storage among the fastest-growing areas.

For investors, the opportunity is increasingly concentrated in assets with scarce capacity, reliable power access, proven demand, and durable cash flows rather than infrastructure scale alone. China illustrates both the potential and the constraints: data centre investment is accelerating, but state ownership, policy exposure, and execution risk may push private capital toward partnerships, operating platforms and supporting infrastructure.

Office occupiers across Asia Pacific have entered a new phase of workplace transformation as office attendance stabilises, AI adoption accelerates, and companies increasingly prioritise premium office space. CBRE’s 2026 Asia Pacific Office Occupier Survey finds that half the respondents expect their office space to expand over the next three years.
 
The survey provides insights from more than 650 corporate real estate executives in the region on their workplace priorities and strategies, growth plans and AI adoption.

Following the weak payroll number for July (originally negative but revised up to slightly positive), August payrolls rose 162,000, comfortably above the 53,000-80,000 consensus range, and unemployment held at 4.1%. While some could argue that the type of jobs created were lower wage and still concentrated in education and healthcare, it is clear that this makes the case for a
hold tricky for the Fed.

The upcoming CPI print on the 11th will be closely watched. Couple the jobs numbers with Brent’s round trip, down to USD 94.71 by September 4th after an April 30th high of USD 120.88, then back toward USD 100 in the past week on fresh US-Iran tensions, and the September 15th-16th FOMC is once again a genuine debate between a hike and a hold, not the
hold-with-easing-bias the market had settled into a month ago.

India’s growth story is increasingly being shaped by the capacity of its cities, infrastructure and productive assets to support a larger and more formal economy. Real estate sits at the centre of this transition. It provides the physical infrastructure for households and businesses, creates employment through construction and allied activities, supports manufacturing and services
through commercial and industrial assets, and increasingly enables newer parts of the economy
such as digital infrastructure and organised logistics.

Its importance therefore extends beyond the value of property itself. Real estate influences economic output, employment, capital formation and a wide network of allied industries. These linkages make it an important enabler of Viksit Bharat; improving productive capacity, strengthening investment and creating the physical environment required for sustained economic
growth.

Takeaways from the APREA Philippines Conference

  • Philippine real estate continues to benefit from resilient domestic consumption and economic activity, supporting opportunities across retail, hospitality and logistics, while improving tourism and expanding trade are providing additional demand drivers.
  • Growth is increasingly extending beyond Metro Manila, with Northern, Central and Southern Luzon and parts of the Visayas seeing stronger demand for housing, industrial space and integrated communities.
  • Industrial, logistics, cold storage and data centres offer additional avenues for investment as the Philippine real estate market broadens beyond traditional sectors. Developing institutional-grade assets can help attract first-time foreign investors and establish a transaction track record that encourages further capital inflows.
  • The expansion of REIT-eligible assets beyond traditional property could broaden the Philippine listed real assets market. New rules covering data centres, toll roads, ports and infrastructure vehicles have already generated a pipeline of potential listings and could provide additional capital recycling and exit options.

Please find below the rebalancing results (effective 21 September 2026 start of trading) for the:

  • GPR/APREA Investable 100 Index
  • GPR/APREA Investable REIT 100 Index
  • GPR/APREA Composite Index
  • GPR/APREA Composite REIT Index (indicated with an asterisk)

GPR/APREA Investable 100 Index

INCLUSIONS

AUSCHARTER HALL LONG WALE REIT
AUSCHARTER HALL RETAIL REIT
JPNJAPAN LOGISTICS FUND INC ORD

EXCLUSIONS

CHNCHINA ELECTRONICS OPTICS VALLEY UNION HOLDING CO LTD
CHNLOGAN GROUP CO LTD
CHNSHENZHEN INVESTMENT LTD

GPR/APREA Investable REIT 100 Index

INCLUSIONS

AUSCENTURIA OFFICE REIT
NZLGOODMAN NEW ZEALAND & GOODMAN PROPERTY SERVICES STAPLED

EXCLUSIONS

AUSCROMWELL PROPERTY GROUP
KORLOTTE REIT CO LTD

GPR/APREA Composite Index

INCLUSIONS

MYSAMFIRST REAL ESTATE INVESTM *
MYSAYER HOLDINGS BHD
THAALLY LEASEHOLD REAL ESTATE INVESTMENT TRUST *
THAFUTURE PARK LEASEHOLD PROP F *
THAPRUKSA HOLDING PCL
TWNWE & WIN DEVELOPMENT CO LTD

EXCLUSIONS

CHNAGILE GROUP HOLDINGS LTD
CHNCHINA ELECTRONICS OPTICS VALLEY UNION HOLDING CO LTD
CHNGREATER BAY AREA AI COMPUTING TECH CO LTD
CHNGUANGZHOU R&F PROPERTIES CO LTD
CHNKAISA GROUP HOLDINGS LTD
CHNSHIMAO GROUP HOLDINGS LTD
IDNBAKRIELAND DEVELOPMENT PT

AI is beginning to reduce information asymmetries in real estate, particularly in cross-border investing, making it easier to compare markets, accelerate due diligence, and assess opportunities across Asia Pacific. The early efficiency gains from automation are likely to become less differentiated over time, shifting competitive advantage toward firms that combine proprietary data, market expertise, and operating capabilities.

For institutional investors and asset managers, the larger implication is that AI may influence both asset selection and asset value, particularly where lower operating costs and better market intelligence translate into improved returns. The firms best positioned to benefit will be those that pair technology with strong governance, human judgment, and a workforce capable of applying AI outputs effectively.