APREA Logo

Knowledge Hub

Office occupiers across Asia Pacific have entered a new phase of workplace transformation as office attendance stabilises, AI adoption accelerates, and companies increasingly prioritise premium office space. CBRE’s 2026 Asia Pacific Office Occupier Survey finds that half the respondents expect their office space to expand over the next three years.
 
The survey provides insights from more than 650 corporate real estate executives in the region on their workplace priorities and strategies, growth plans and AI adoption.

Following the weak payroll number for July (originally negative but revised up to slightly positive), August payrolls rose 162,000, comfortably above the 53,000-80,000 consensus range, and unemployment held at 4.1%. While some could argue that the type of jobs created were lower wage and still concentrated in education and healthcare, it is clear that this makes the case for a
hold tricky for the Fed.

The upcoming CPI print on the 11th will be closely watched. Couple the jobs numbers with Brent’s round trip, down to USD 94.71 by September 4th after an April 30th high of USD 120.88, then back toward USD 100 in the past week on fresh US-Iran tensions, and the September 15th-16th FOMC is once again a genuine debate between a hike and a hold, not the
hold-with-easing-bias the market had settled into a month ago.

India’s growth story is increasingly being shaped by the capacity of its cities, infrastructure and productive assets to support a larger and more formal economy. Real estate sits at the centre of this transition. It provides the physical infrastructure for households and businesses, creates employment through construction and allied activities, supports manufacturing and services
through commercial and industrial assets, and increasingly enables newer parts of the economy
such as digital infrastructure and organised logistics.

Its importance therefore extends beyond the value of property itself. Real estate influences economic output, employment, capital formation and a wide network of allied industries. These linkages make it an important enabler of Viksit Bharat; improving productive capacity, strengthening investment and creating the physical environment required for sustained economic
growth.

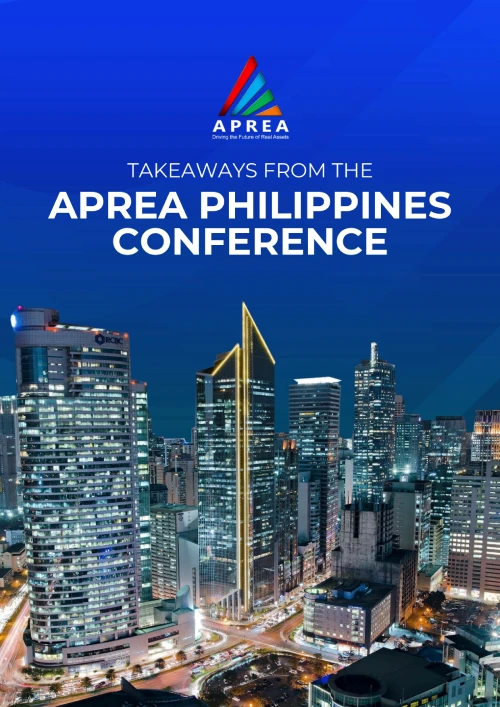
Takeaways from the APREA Philippines Conference

  • Philippine real estate continues to benefit from resilient domestic consumption and economic activity, supporting opportunities across retail, hospitality and logistics, while improving tourism and expanding trade are providing additional demand drivers.
  • Growth is increasingly extending beyond Metro Manila, with Northern, Central and Southern Luzon and parts of the Visayas seeing stronger demand for housing, industrial space and integrated communities.
  • Industrial, logistics, cold storage and data centres offer additional avenues for investment as the Philippine real estate market broadens beyond traditional sectors. Developing institutional-grade assets can help attract first-time foreign investors and establish a transaction track record that encourages further capital inflows.
  • The expansion of REIT-eligible assets beyond traditional property could broaden the Philippine listed real assets market. New rules covering data centres, toll roads, ports and infrastructure vehicles have already generated a pipeline of potential listings and could provide additional capital recycling and exit options.

Please find below the rebalancing results (effective 21 September 2026 start of trading) for the:

  • GPR/APREA Investable 100 Index
  • GPR/APREA Investable REIT 100 Index
  • GPR/APREA Composite Index
  • GPR/APREA Composite REIT Index (indicated with an asterisk)

GPR/APREA Investable 100 Index

INCLUSIONS

AUSCHARTER HALL LONG WALE REIT
AUSCHARTER HALL RETAIL REIT
JPNJAPAN LOGISTICS FUND INC ORD

EXCLUSIONS

CHNCHINA ELECTRONICS OPTICS VALLEY UNION HOLDING CO LTD
CHNLOGAN GROUP CO LTD
CHNSHENZHEN INVESTMENT LTD

GPR/APREA Investable REIT 100 Index

INCLUSIONS

AUSCENTURIA OFFICE REIT
NZLGOODMAN NEW ZEALAND & GOODMAN PROPERTY SERVICES STAPLED

EXCLUSIONS

AUSCROMWELL PROPERTY GROUP
KORLOTTE REIT CO LTD

GPR/APREA Composite Index

INCLUSIONS

MYSAMFIRST REAL ESTATE INVESTM *
MYSAYER HOLDINGS BHD
THAALLY LEASEHOLD REAL ESTATE INVESTMENT TRUST *
THAFUTURE PARK LEASEHOLD PROP F *
THAPRUKSA HOLDING PCL
TWNWE & WIN DEVELOPMENT CO LTD

EXCLUSIONS

CHNAGILE GROUP HOLDINGS LTD
CHNCHINA ELECTRONICS OPTICS VALLEY UNION HOLDING CO LTD
CHNGREATER BAY AREA AI COMPUTING TECH CO LTD
CHNGUANGZHOU R&F PROPERTIES CO LTD
CHNKAISA GROUP HOLDINGS LTD
CHNSHIMAO GROUP HOLDINGS LTD
IDNBAKRIELAND DEVELOPMENT PT

AI is beginning to reduce information asymmetries in real estate, particularly in cross-border investing, making it easier to compare markets, accelerate due diligence, and assess opportunities across Asia Pacific. The early efficiency gains from automation are likely to become less differentiated over time, shifting competitive advantage toward firms that combine proprietary data, market expertise, and operating capabilities.

For institutional investors and asset managers, the larger implication is that AI may influence both asset selection and asset value, particularly where lower operating costs and better market intelligence translate into improved returns. The firms best positioned to benefit will be those that pair technology with strong governance, human judgment, and a workforce capable of applying AI outputs effectively.

Summary:

As the year unfolds, conflict is becoming a defining global theme. Whether in trade, technology or geopolitics, competition and confrontation are increasingly shaping the economic outlook. Beginning in Iran, hostilities resumed in July following a brief respite, sending energy prices sharply higher in the process. The global economy has so far proven resilient to what Fatih Birol, head of the International Energy Agency, described as the “biggest energy security threat in history”. This resilience reflects weaker energy demand, particularly across Asia Pacific, as well as a substantial drawdown in global inventories, helping to keep the market broadly balanced.

However, reserves have fallen sharply, with inventories held by OECD nations reaching their lowest level since 1990, even before the recent US Iran framework agreement. This places renewed focus on the duration of the conflict, as the oil market’s ability to absorb disruption will diminish over time. The likely result is greater price volatility (even if we get a new deal), with implications extending well beyond energy markets through inflation, consumer and business sentiment, and the fiscal and monetary policy outlook.

Key Takeaways

Climate adaptation is a business necessity and should no longer require debate or justification

Panellists stressed that organisations are already experiencing climate impacts, such as productivity loss and vulnerability of assets, and should move beyond debating whether adaptation is necessary. The focus should be on planning and scaling solutions to protect assets, operations and long-term business viability rather than convincing leadership that climate risks are a threat to the business.

Bridging the gap between climate risk assessment and investment requires adaptation to be expressed in financial terms

While many organisations are conducting climate risk assessments, translating findings into action remains challenging. Securing investment requires a clear business case that quantifies financial value of adaptation through metrics such as avoided losses, energy savings, carbon pricing, and asset value protection. Timing this process with financial windows is also vital to ensure that solutions are actionable with appropriate investment. Adaptation initiatives are more likely to secure investment when benefits are articulated in financial terms and aligned with existing capital planning cycles.

Key findings include:

  • 85% of investors expect to increase Living investment over the next five years.
  • Investors are increasingly favouring stabilised, income-producing and defensive Living assets. Recent volatility has prompted half of respondents to report a greater preference for stabilised, income-producing assets, yet only 17% expect stabilised acquisitions to be their most likely deal structure over the next one to three years, reflecting the limited availability of institutional-grade stock outside Japan. The resulting imbalance, combined with a challenging development environment, is pushing capital towards alternative routes to market, with 73% actively considering repositioning or change-of-use strategies.
  • Australia/New Zealand and Japan rank clearly ahead of other APAC markets for prospective investment, reflecting the combination of institutional scale in Japan and housing undersupply underpinning growth potential in Australia.
  • Market opacity remains a constraint on investment. The buyer-seller pricing gap is the leading investment challenge, identified by 44% of respondents, followed by development viability (29%). Limited transaction evidence and inconsistent transparency are making it harder for investors to price assets and deploy capital.

Data centres have become a core pillar of infrastructure investment across Asia Pacific.

Driven by AI adoption, cloud expansion, enterprise digital transformation, and digital sovereignty initiatives, the sector continues to attract significant capital. At the same time, constraints around power, land, and development capacity are reshaping how investors, operators, and developers identify and secure growth opportunities.

As competition intensifies across the digital infrastructure sector, access to reliable market intelligence and robust investment benchmarks remains limited in many Asia Pacific markets. Understanding the forces shaping performance, risk, and long-term value creation has never been more important.

The latest edition of the Asia Pacific Data Centre Investment Landscape 2026 provides a comprehensive analysis of the trends transforming the region’s data centre sector, with insights spanning 14 key markets.

Download the report to gain insights into:

  • Where capital is flowing across Asia Pacific’s data centre markets
  • Which locations are emerging as the region’s next digital infrastructure hubs
  • The key drivers shaping investment decisions and market performance
  • Trends that will define future growth and value creation opportunities