
APREA Logo

Knowledge Hub

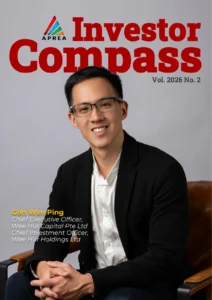
Goh Wee Ping on

Leadership, Discipline and Real Assets Growth

In APREA’s Real Assets, Real People, we speak with leaders shaping the future of Asia Pacific’s real assets industry, exploring the ideas, decisions and leadership principles behind their organisations’ growth. In this edition, Goh Wee Ping shares his perspectives on the shift from real estate assets to operating platforms, the growth of PBSA, the role of AI, and what it takes to build resilient businesses beyond market cycles.
“Asia Pacific remains a key growth engine for branded residences, but its next chapter will be defined by the breadth of its markets,
not the scale of its leading ones.”

Asia Pacific is currently the second most established branded residential region globally, accounting for approximately 23% of all completed schemes worldwide. Whilst the region continues to demonstrate impressive momentum, with a further 187 projects expected to be delivered by 2032, the nature of its growth story is evolving. Although substantial in absolute terms, this growth rate of 97% is level with the Americas and falls behind both Europe and, most notably, the Middle East and Africa, which has emerged as the industry’s fastest- growing region.

Rates set the direction, not fundamentals. Leasing is strong and supply is tight across the region, but neither re-rates the sector while the regional rate path stays hostage to oil and therefore to the Gulf. The August 7th US payroll print (-23,000, with 103,000 of downward revisions and average hourly earnings at 3.2% YoY, the softest since May 2021) cut September hike pricing to 42-44% and pushed the risk to October. Core CPI is stable at 2.6% and justifies a hold.

Japan. Results are done and mixed. Mitsui Fudosan’s 1Q fall was pre-guided, with every greater-Tokyo renewal this fiscal year settled at a higher rent. Tokyo Tatemono beat and raised to record guidance on a JPY 26.1bn property sales gain, but residential operating profit fell 83.2%, which undercuts the argument that condominiums are unaffected by higher rates. Central-five-ward asking rents have accelerated to +11.4% YoY from +5.5% in December 2025. The constraint is the BOJ at 1.00%; consensus sees 1.25% by December and we would not be surprised by September. Sankei Building first-round bids near JPY 1tn against a JPY 500-800bn expectation argue against cap rate softening.

Australia. Guidance is the risk into full-year reporting, not results. Stockland and Mirvac have corrected on residential and EV/EBITDA is back to just above 2022 trough levels, but hedge ratios are higher than in 2022 and in-place debt costs are already high, so we do not expect material deterioration.

Hong Kong. Mid-market residential is supported by end-user demand while luxury continues to suffer. Capital returns are the theme: Wharf REIC lifted its payout ratio to 90% and the stock closed up 13.7%, Link has committed disposal proceeds to buybacks, and we have written to Fortune REIT urging the same treatment of Stars of Kovan proceeds.

Singapore. A non-event, with CICT on August 12th the last major report. Paragon at a 3.9% entry yield against Asia Square Tower 2 at 3.0% lifts pro forma FY25 DPU 2.1%.

India’s renewable energy sector has witnessed unprecedented growth over the past decade, driven by ambitious policy reforms, declining technology costs, and strong investor participation. With installed renewable energy capacity expanding rapidly and the country targeting 500 GW of non-fossil fuel capacity by 2030, the sector is expected to require investments exceeding USD 190-215 bn over the remainder of the decade. While traditional funding sources such as project debt, private equity, strategic investments, and foreign direct investment have played a pivotal role in supporting this growth, sustaining the next phase of expansion will require more efficient mechanisms for capital recycling.

KEY TAKEAWAYS

  • A total of 22,290 rental contracts of island-wide private residential properties (excluding ECs) commenced during the quarter, up 5.1% from the 21,203 contracts recorded in the previous quarter.
  • The URA rental index for non-landed private residential properties rose 0.4% QoQ.
  • Based on Savills basket of high-end non-landed residential properties, the average monthly rent continued its upward trajectory, rising by 1.4% QoQ.
  • Despite limited new completions, the overall vacancy rate of completed private residential properties (excluding ECs) rose to 6.4% in Q2/2026.
  • While Singapore’s economic growth in 2026 is expected to outperform the official 2% to 4% forecast, the benefits to the residential leasing market may be limited. Mixed free cash flow trends among MNCs could restrain expatriate deployment overseas, while the removal of the 15-month wait-out period for private homeowners moving to HDB flats may reduce domestic leasing demand. Accordingly, we maintain our view that private residential rents will remain broadly flat in 2026.

The global data centre sector has emerged from a pivotal year in digital infrastructure, underpinned by continuous cloud migration and digitisation, combined with the proliferation of artificial intelligence, super-charging demand for data centre infrastructure. Across the globe, real estate transaction volumes, comprising single-asset-sales and development site acquisitions, totalled $16.5 billion in 2025 with development site acquisition volumes in particular surging 12.4% on 2024 volumes, the highest annual investment tally to date. Similarly, Knight Frank’s bespoke data centre appraisals valued the global stabilised data centre market at $1.95 trillion, a 39.3% increase on 2024. Looking ahead, 48GW is expected to be delivered between 2026 and 2029, representing a 77% increase in global supply volumes. Within this, AI supply volumes are set to expand from 8GW to 27GW, growing to 24.5% of total live IT.

Key Takeaways

  • Living sectors are going mainstream: Institutional capital is increasingly flowing into co-living, BTR, student accommodation and senior housing across APAC.
  • Significant growth runway remains: APAC accounts for around 60% of the world’s population but attracted only 12% of global living-sector capital in 2025, highlighting a substantial allocation gap.
  • Demand continues to outpace supply: Major markets across the region face shortages of professionally managed rental housing, creating long-term opportunities for investors.
  • Market-specific opportunities are emerging: The report highlights strong growth potential in Singapore co-living, Australia BTR, Hong Kong student housing and India’s rapidly expanding PBSA sector.
  • Operational expertise is becoming a key differentiator: Investors are increasingly combining capital with local partnerships, platform strategies and operating capabilities to create scale and drive performance.

KEY TAKEAWAYS

  • Strong demand for premium office space, coupled with the limited supply of new office developments, has led to a two-tier leasing market. While premium office buildings continue to enjoy healthy occupancy levels and rental growth, lower-quality buildings face greater challenges in attracting and retaining tenants
  • Based on data compiled by Savills, the vacancy rate for CBD Grade A offices declined for the third consecutive quarter by 1.0 percentage point (ppt) quarteron-quarter (QoQ) to 5.6% in Q2/2026. This was the lowest since Q3/2022 when vacancy rate was at 5.2%.
  • With vacancy rates remaining tight, particularly in premium grade office buildings, and with limited upcoming supply, landlords have maintained a firm stance on both asking and renewal rents. This has led to average CBD Grade A office rents to increase further by 2.8% QoQ to S$10.42 per sq ft in the quarter.
  • Barring a significant deterioration in the political-economic sphere, even a marginal increase in office demand could result in disproportionately strong rental growth given the current supply constraints. Accordingly, we are revising our 2026 rental growth forecast upward from 3%–5% to 5%, while projecting a further 5%–7% year-on-year (YoY) increase in 2027.

India’s real estate market is broadening beyond office leasing, with economic growth, digitalisation, manufacturing, and infrastructure investment supporting sustained institutional interest across logistics, data centres, industrial parks, retail, and residential assets.

Record demand from Global Capability Centres (GCCs) is reshaping office requirements, driving occupiers toward high-quality, technology-enabled campuses and reinforcing demand for institutional-grade properties.

India’s REIT market is also maturing, where investors are placing greater emphasis on governance, asset quality, and capital allocation. Overall, resilient occupier demand, expanding domestic capital pools, and selective institutional investment continue to support a constructive long-term outlook for India’s real assets market.
